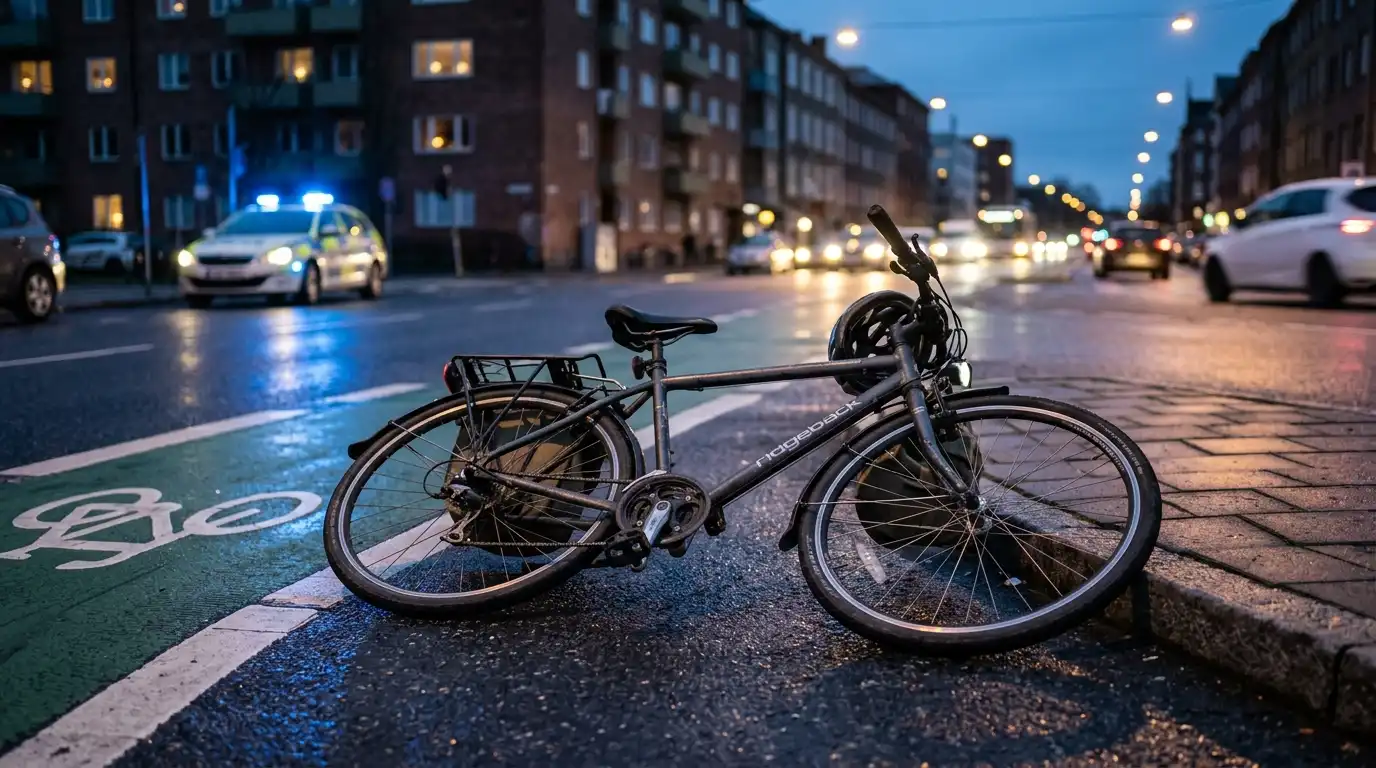
A hit-and-run crash is one of the most frightening scenarios a cyclist can face. Beyond the immediate physical shock and potential injury, the absence of an identified driver leaves a critical question: who pays for medical bills, lost wages, and property damage? When the responsible party flees the scene, navigating insurance coverage can feel like navigating a complex legal maze.
Many cyclists assume that if they were not driving a car at the time of the incident, motor vehicle insurance policies do not apply. However, auto insurance plays a primary role in securing financial recovery after a bicycle hit-and-run. Understanding how auto, health, and specialized bicycle insurance policies interact is essential for every road user.
The Power of Uninsured Motorist (UM) Coverage
When an at-fault driver flees without leaving contact or insurance details, the legal system treats the fleeing driver as an uninsured motorist. For cyclists who own a motor vehicle—or live in a household with a family member who owns one—their personal Uninsured Motorist (UM) coverage is typically the first line of defense.
Because auto insurance policies follow the insured person rather than the physical vehicle, your UM policy generally extends to you while you are walking, riding a scooter, or cycling on public roads. According to guidance from the National Association of Insurance Commissioners (NAIC), Uninsured Motorist coverage is designed to step into the shoes of the missing driver’s insurance, paying out damages that the at-fault driver would have legally owed you.
Key benefits covered under Uninsured Motorist policies include:
- Medical Expenses: Emergency room visits, hospital stays, surgeries, physical therapy, and ongoing prescription costs resulting from the crash.
- Lost Wages: Compensation for income missed due to injury recovery, hospitalizations, or temporary disability.
- Pain and Suffering: Non-economic damages for physical pain, emotional distress, and reduced quality of life caused by the collision.
It is vital to check your policy’s limits. Carrying minimum statutory limits may leave you underinsured in the event of a severe crash, making higher UM/UIM limits one of the most cost-effective investments a cyclist can make.
Personal Injury Protection (PIP) and MedPay
Depending on your state or regional laws, your auto policy may include no-fault coverage options like Personal Injury Protection (PIP) or Medical Payments (MedPay). Unlike general liability claims, PIP and MedPay pay out regardless of who caused the crash and do not require proving fault before receiving benefits.
In no-fault insurance states, PIP is often mandatory and provides immediate reimbursement for medical bills and lost earnings up to the policy cap. MedPay functions similarly, covering reasonable medical and funeral expenses resulting from a collision. In hit-and-run cases, accessing PIP or MedPay can help cover immediate out-of-pocket costs while larger insurance investigations proceed.
What If You Do Not Own a Car?
Cyclists who do not own a vehicle or reside with an insured family member face a different set of options following a hit-and-run. Fortunately, several secondary insurance pathways remain available:
1. Household Family Member Policies
In many jurisdictions, auto insurance coverage extends to resident relatives. If you live with parents, a spouse, or immediate family members who maintain auto insurance with UM coverage, you may be covered under their policy as a relative residing in the same household.
2. Standalone Bicycle Insurance
Specialized bicycle insurance policies have grown increasingly popular among commuters and distance cyclists. These policies act as standalone coverage tailored specifically to cycling risks. Many dedicated bike policies include built-in hit-and-run coverage, crash damage protection for high-end bicycles, and personal liability coverage without requiring a primary auto policy.
3. Health Insurance
If no auto or dedicated bicycle insurance coverage is available, your health insurance policy becomes the primary coverage for your medical care. Health insurance will pay for hospital visits, doctor care, and rehabilitation according to your standard co-pays, deductibles, and network restrictions. Keep in mind that health insurance only covers medical treatment—it will not compensate you for lost wages, pain and suffering, or bicycle repair costs.
4. State Crime Victims Compensation Funds
Because leaving the scene of an accident is a criminal act, hit-and-run victims may qualify for assistance through state-sponsored Crime Victims Compensation programs. These funds are designed to assist victims of violent crime or hit-and-run offenses with medical bills and lost wages when no other insurance sources exist.
Step-by-Step: Protecting Your Claim After a Hit-and-Run
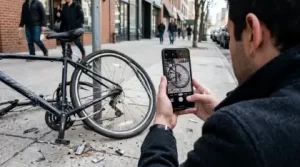
Securing insurance coverage after a hit-and-run requires meticulous documentation and quick action. Insurance adjusters evaluate hit-and-run claims under strict scrutiny to prevent fraud, making immediate reporting critical.
- File an Immediate Police Report: Most auto insurance policies strictly require a formal police report to process a hit-and-run UM claim—often within 24 to 72 hours of the incident. Ensure law enforcement documents the crash as a hit-and-run.
- Gather Eyewitness Contact Details: Eyewitness statements are crucial for establishing that a physical collision occurred with a fleeing vehicle. Collect names, phone numbers, and statements from bystanders, shopkeepers, or other road users.
- Document the Scene and Gear: Take detailed, high-resolution photographs of your physical injuries, damage to your bicycle, torn clothing, and any paint transfer or debris left on the road by the fleeing vehicle.
- Check for Surveillance Cameras: Look for nearby traffic cameras, municipal transit cameras, security cameras on local businesses, or doorbell cameras on residential homes that may have captured the vehicle’s license plate or description.
- Notify Your Insurance Provider Promptly: Inform your insurer about the incident as soon as possible. Clearly state that you were involved in a hit-and-run while riding your bicycle and intend to open a claim under your Uninsured Motorist coverage.
Know Your Legal Rights and Policy Terms
Navigating the aftermath of a hit-and-run is physically and emotionally demanding. By reviewing your current auto and health insurance policies today, you can identify coverage gaps, adjust your Uninsured Motorist limits, and ensure that you remain fully protected every time you hit the road.